September 16, 2026/CSL Report
DPRP – Africa’s First Mega Refinery
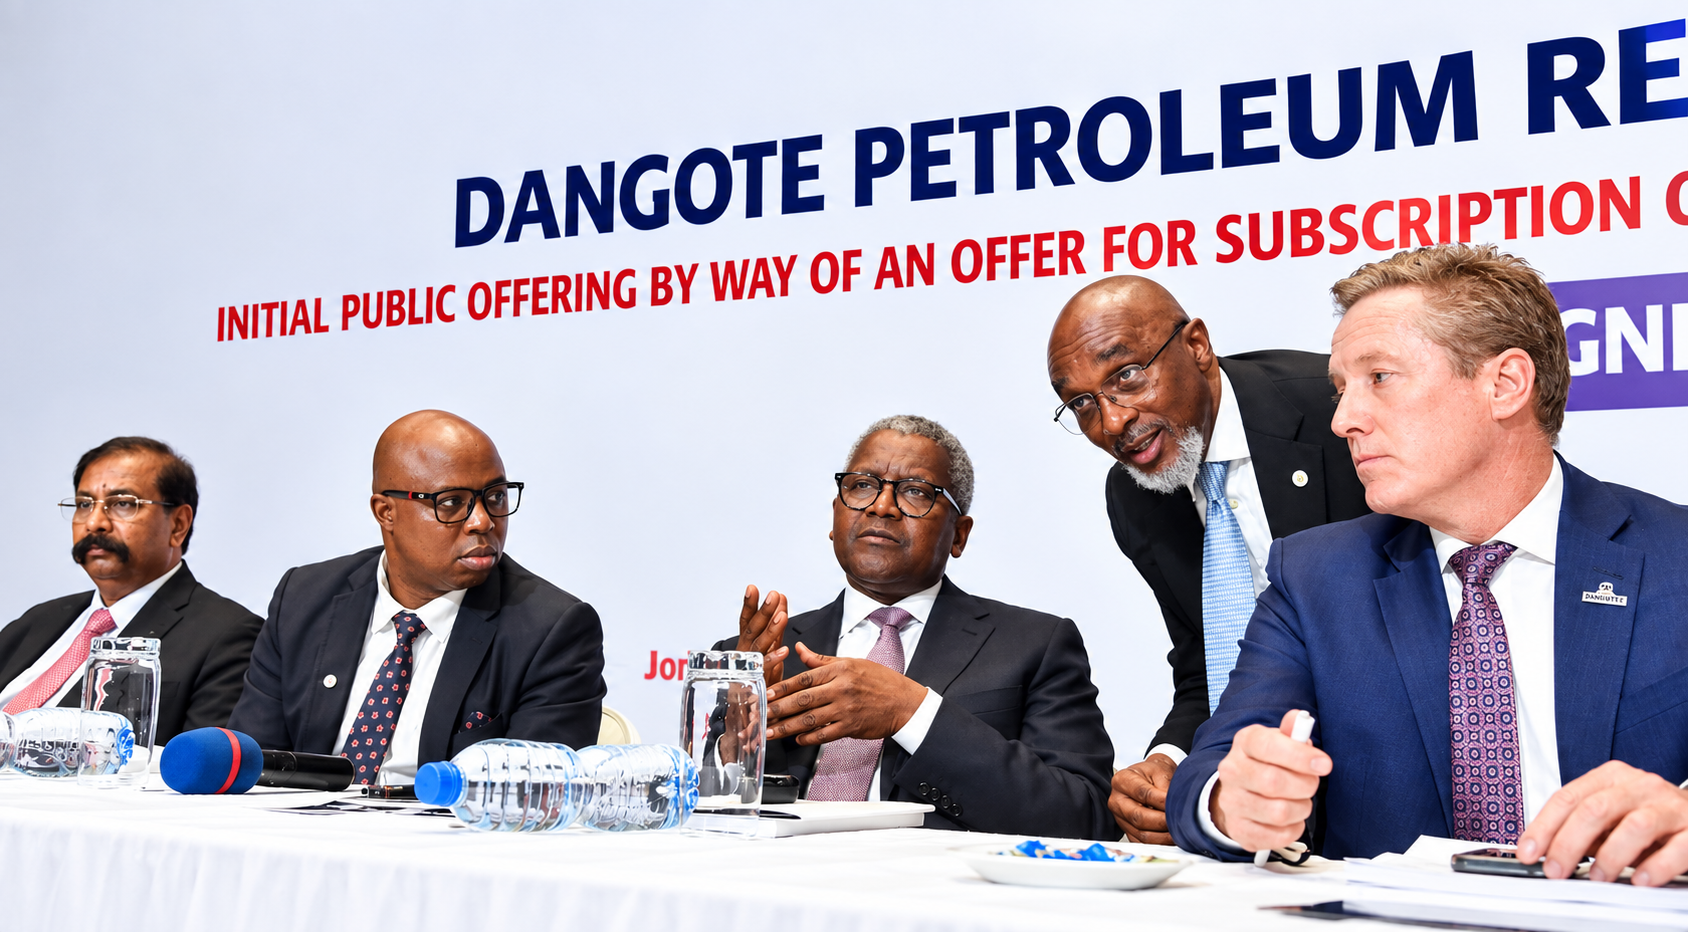
We initiate coverage of Dangote Petroleum Refinery & Petrochemicals FZE (DPRP) with a BUY recommendation and a 12-month target price of approximately ₦767.29/share on the 124.229bn post-IPO share count using ₦1,326.30/US$. Against the ₦525 offer price, this implies approximately 46.2% upside. The core investment thesis rests not simply on the scale of DPRP, but on its unique combination of scale, processing complexity, vertical integration, and route-to-market control within a structurally undersupplied region.
The refinery was commissioned commercially in January 2024, achieved its original 650 thousand barrel per day (kbpd) performance test in February 2026, and subsequently demonstrated throughput of up to 700kbpd in June 2026. The complex also has 830 thousand tonnes per annum (ktpa) polypropylene and approximately 77ktpa sulphur capacity. For the Phase 2 expansion drive, Dangote plans to add 750,000 bpd of refining capacity, taking the refinery from 650,000 bpd to 1.4mbpd by 2029, potentially making it the world’s largest single-site refinery.
DPRP recently transitioned into profitability after recording bottom-line loss positions of US$1.5bn and US$0.5bn in FY 2024 and FY 2025 respectively. H1 2026 reflected an inflection point with revenue rising to US$13.9bn, gross profit to US$2.5bn and profit after tax (PAT) to US$1.8bn. The sharp improvement reflects higher throughput, better product mix and strong refined-product pricing.
However, it is worth mentioning that H1 margins were supported by an unusually tight global product market. Therefore, the long-term investment case hinges on whether the refinery’s structural cost and yield advantages remain intact as refining margins normalise.
Phase 2 represents the next significant value creation opportunity. The management highlights an expansion to approximately 1.4mbpd and a total programme cost of about US$14.3bn, with the IPO providing ₦2.111 trillion (tn) – approximately US$1.548bn using the Prospectus’s ₦1,364/US$ reference – of net proceeds toward growth capex. This is about 10.8% of the estimated Phase 2 project cost. The balance is expected to be funded through internal cash generation and additional financing sources, including debt, trade and project financing arrangements as deemed appropriate by DPRP management.
The four variables we would monitor most closely in relation to the expansion and its positive effect on investors are: (1) sustained utilisation and technical availability; (2) crude availability and delivered feedstock cost; (3) normalised gross refinery margin (GRM) and product cracks; and (4) Phase 2 capital expenditure (CapEx), financing and commissioning milestones.
Click here to download full report: CSL Dangote Petroleum Refinery Initiation of Coverage