November 9, 2026/Cordros Report
The Cordros Pantry Index (CPI), formerly the Cordros Jollof Index, fell to 61.38 points in October 2026 from 70.40 in September, as lower prices for rice and chicken, along with selected seasonings, more than offset increases in some vegetables and flavourings. Consequently, the cost of preparing the pantry dish declined by 3.5% to NGN22,276.81.
However, affordability remained in the “Critical” category, indicating that the reduction in preparation costs was insufficient to materially improve the affordability assessment. Looking ahead, we expect food prices to edge higher as the seasonal supply boost gradually fades and festive demand strengthens, particularly for high-weight items such as rice and chicken, as well as selected vegetables. The outlook assumes relative exchange-rate stability and improved security conditions across key food-producing regions.
The CPI fell to 61.38 points in October 2026 from 70.40 points in September, representing a month-on-month (m/m) decline of 9.02 index points. This decline was driven primarily by lower prices for key items, including rice, chicken, seasonings and Liquefied Petroleum Gas (LPG). As illustrated in Figure 2, movements in the index have broadly tracked the direction of food inflation reported by the National Bureau of Statistics (NBS).
From an affordability perspective, this index indicates that the cost of preparing the pantry dish remained elevated and stayed in the Critical category. This suggests that the decline in the basket cost was insufficient to move the index out of its second-most-severe affordability classification.
In absolute terms, the cost of preparing the pantry dish declined to NGN22,276.81, from NGN23,077.76 in September. This represents a 3.5% m/m decline, reflecting lower prices for several key food items. Seasonal supply improvements in selected vegetables, including tomatoes, red bell peppers and onions, along with some seasonings, also influenced the basket’s price movement. Together, these movements reduced the cost of preparing the dish in October 2026.
Basket Composition and Price Movements
In October 2026, the decline in the overall index was driven primarily by lower prices for rice, protein products, and energy. Together, these categories account for about 77.0% of the basket weight. However, much of the decline was partly offset by higher prices for selected vegetables, including red bell peppers, vegetable oil, fresh garlic and tomato paste.
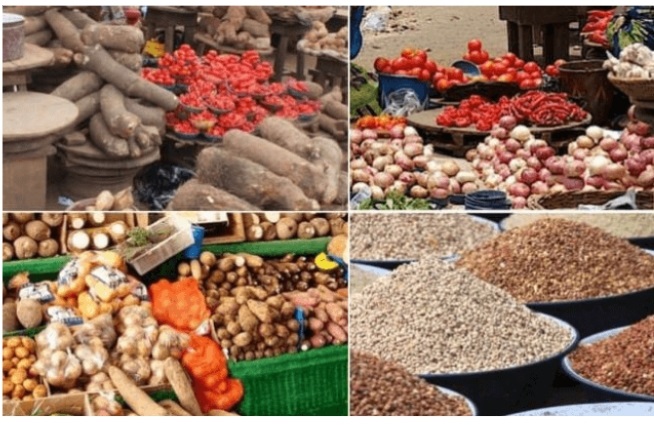
Prices of tomato paste, vegetable oil and scotch bonnet peppers rose by 4.5%, 7.8% and 8.8% m/m, respectively. Improved supply following above average main season harvest supported lower prices for selected agricultural products, although this effect was not uniform across the vegetable and flavouring components of the basket. Relatively stable fertiliser and fuel costs also helped contain agricultural production and transportation costs in October.
Interpretation
The October 2026 reading highlights an important feature of the basket: Price increases and declines are concentrated across different categories and have asymmetric effects on the overall index and on the cost of preparing the dish. The categories recording price declines, particularly grains, protein and energy, are also those that have benefitted from improved supply conditions and relative exchange rate stability. Rice (-8.2%) and chicken (-7.5%), both relatively high- weight items in the basket, accounted for a substantial share of the 9.02 points fall in the index. Cooking gas prices were broadly unchanged during the month. By contrast, price increases were concentrated in items such as tomato paste (+4.5%), fresh garlic (+3.7%), and vegetable oil (+7.8%). Their relatively low weights limited their contribution to the overall index, although their effect on total preparation costs depends on their respective shares of recipe costs.
The price structure also signals the nature of the shock: Items recording price declines are generally more closely linked to national distribution networks and, in some cases, imported supply or fuel-related costs. Improved domestic availability and relative exchange rate stability may have supported price moderation, in part by easing the cost of imported food products and production inputs. By contrast, the items whose prices decreased are closely tied to domestic dry-season cultivation. Their perishability and geographic concentration in northern Nigeria make their prices more sensitive to seasonal and logistical disruption. This distinction is important because it suggests that further moderation in these prices would depend primarily on improved harvest, distribution and logistics.
Conclusion
The October 2026 reading highlights the role of seasonal supply conditions in the decline in the pantry index and the cost of preparing the dish. Lower prices for staples and energy drove the pantry Index down by 9.02 points to 61.38 in October. The key finding is that lower prices for high-weight, tradable items more than offset increases in selected lower-weight perishables. Because the pressure-easing factors are primarily supply-side and seasonal, reflecting bumper main harvests. Until the main harvest impacts fade in late November, lower prices for perishable items are likely to continue to keep the index estimates and the total cost of the dish down.